Rate Hold vs Pre-Approval - A Common Misconception
Michael Hallett • May 29, 2015
mis-con-cep-tion (noun)
- a view or opinion that is incorrect because it is based on faulty thinking or understanding; mistaken notion; an erroneous conception.
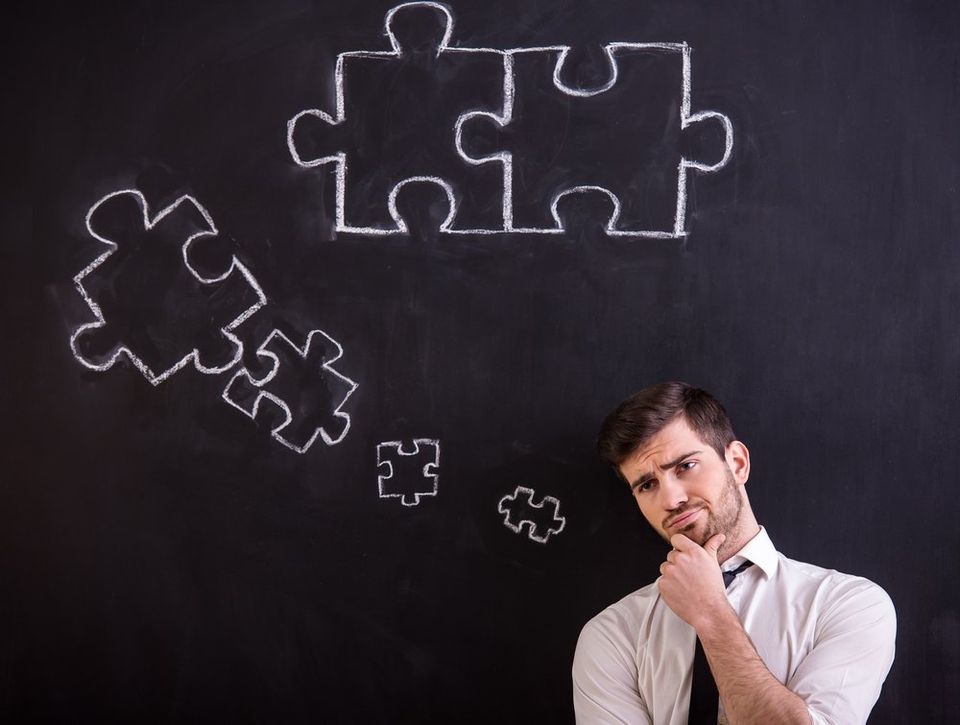
With not knowing how to start this particular blog post, I decided to look for some images that might summarize the topic best - What is the difference between a RATE HOLD and a PRE-APPROVAL?
I thought this picture 100% represented how these terms are perceived, you say one thing but you mean the opposite. For most people the term PRE-APPROVAL is more commonly used than the latter. The term RATE HOLD is generally only used in the broker/lender sphere.
Many years ago (seems like the ice age ago) one could place a phone call to their personal banker and lock in a mortgage, then it switched to only requiring a paystub maybe a bank stmt and T4s. Whereas now one requires their entire biography and proof of net worth followed by a blood sample... somewhat facetious, but there is more involved as lenders need to make an accurate risk assessment.
Times have changed and so should our line of thinking. Underwriting mortgages is not cheap and lenders have upfront costs that take years to recoup.
Rate Hold
These are generally automated where nobody even looks at the application. The system only analyzes basic criteria; beacon score, loan-to-value, name and birthdate. No documents are even reviewed. A rate hold is simply just that, a rate hold. It's just a certificate guaranteeing the stated rate for a stated period of time, usually to a maximum of 120 days. Rate holds are mostly utilized for borrowers who are going to purchase or refinance in the near future.
Pre-Approval
The pre-approval approach is generally a more detailed process, with all documents being reviewed, except for the subject property. The lender will have to approve the covenant based on the information provided such as employment, source of the down payment and credit history criteria. Approval of these three pillars is NOT a guarantee that the mortgage application will be approved. The lender still has to do it's due diligence on the fourth pillar (subject property) as it must still meet all the lenders guidelines and insurer if there is less than a 20% down payment.
The most common question you will hear during the purchase process is, ARE YOU PRE-APPROVED?
In my short 6 year tenure I have to worked with numerous clients that thought they were PRE-APPROVED by their 'bank.' But during the subject removal timeline found out that they were NOT pre-approved, all for various reasons. Instead there should be a series of questions asked:
- Have you consulted with your Mortgage Expert?
- If so, when was the last time you had a conversation with her/him?
- Is there a rate hold or pre-approval in place? Do you understand the difference(s)?
- Have you sent her/him your complete package of documents that was requested?
- Are there any changes to employment, credit, the down payment or the purchase price?
- Have you discussed the 'plan' for this property? This will determine the term and mortgage product chosen.
- ...and much more...
As you can see there is much more to consider than just, ARE YOU PRE-APPROVED?
No one mortgage is exactly the same as someone else's. The mortgage process is a complex labyrinth of puzzles pieces that have to fit together perfectly. Note that the puzzle pieces are constantly changing in this industry.
Due to the steep underwriting costs of each mortgage application most lenders are electing to follow the RATE HOLD process. By analyzing a complete 4 Pillar mortgage application package (credit, employment, down payment and subject property) the lender is able to maximize dollars spent to acquire a new client. Navigating the RATE HOLD/PRE-APPROVAL process should be left up to your trusted Mortgage Expert.
The best PRE-APPROVAL is the one that comes from your Mortgage Expert because they can analyze and do a pre-underwrite even before doing a RATE HOLD. With their expert advice you can construct a strategy that is tailored to your specifically to your mortgage financing scenario.
If you have any questions, please don't hesitate to contact me anytime!
SHARE
MY INSTAGRAM

One of the most common questions, “how long does it take to get pre-qualified?” My response, “how fast can you provide the information I need.”

Playing in the forest today. Always fun exploring. #mountainbikingmortgagebroker

Mortgage Brokering meets mountain biking and craft beer. A couple months ago I set for a bike ride with the intention of answering few mortgage related questions, mission accomplished. Any good bike ride pairs nicely with a tasty beer which we enjoyed @parksidebrewery. Hope you see the passion I have for brokering, biking and beer. @torcabikes #mountainbikingmortgagebroker

My thighs were cold all day, it was ‘that’ deep. I was choking on snow all day.

The weather report was 36 cm of new snow, it was more like 45-50 cm of light deep powder. Insane day of skiing.

Spotted a ski-bunny today @kirstinjhallett so I trapped ‘er. 📸 credit @troy.hartley

Aidan leading the pack up the Lemming Line in seek of fine fresh powder.

Beautiful British Columbia! A cold winter day at its finest.

Aidan and I braved the -19C temperature and windy conditions for the boot to knee deep turns...it was a no-brainer.

Happy Holidays. Seasons Greetings. Merry Christmas. All the best from Kirstin, Aidan and Michael. Enjoy your family time.

Snow report for today was boot to knee deep in places. Simply an awesome day rippin’ with the kids, I had to show them that I still got it. 📷 credit @jhalskiing

It’s that time of year for my annual post, the Christmas Tree pilgrimage. The only that changes year after year is that Aidan gets taller! Not to worry though, the Canadian tuxedo jacket remains the same. HAPPY HOLIDAYS everyone. Much love to all.

Fresh wood in the morning...where is this treasure trail going to take me?

TEASER alert...at thats what I think they call it in the business. Years ago a wrote a blog called BEERS BIKES AND MORTGAGES. I some how (in my head) blended all 3 topics into 1 blog. Simply put, I enjoy aspects of all 3 with each of them providing something different. I re-united with the talented Regan Payne on a project that I think will shed a bit more light on who I am and what I do. #craftbeer #mountainbike #mortgagebrokerbc #dlccanadainc

Here is to looking forward past injuries, feels good to be riding again. It was a 18 week grind!

Extreme tubing, watch until the end. Aidan manages to hold on.

Lake life as a passenger is a good life. Captain @kirstinjhallett . #woodlake #kalamakalake

Yet another reason why our license plates say BEAUTIFUL BRITISH COLUMBIA on them. An evening enjoy the view on Pitt Lake.

Surfing! Don’t need functioning hands to surf. It was nice to do something active. Thanks @jordspring #sakinaw

Good thing there were a few other vehicles with winches on the front.

He was OK, thumbs up. The roll cage and 5-point seat belt did its job.

My sons intro to operating a side-by-side on his own. Watch to the end.

The Lookout over looking Tulameen BC. Took some 4x4ing to get there, but we did it.

The day started out great. Exploring the back country roads of BC, Stave Lake area. Views of Alouette Lake in the background

Impromptu ride on Burke. I dreamed of the day Aidan would ask to go for a ride...today was the day, “Dad do you want to go for a ride?” Heck ya, let’s go! This was a fun feature at the end.

An afternoon of exploring the Stave Lake zone. Planning to return soon once the snow melts to get some vertical.

Found a fun little gap-drop to session. I have my moments when I like my tires leaving the ground.

This would have been a fun stunt once upon a time!

And so it begins...another tool for adventuring! So different so fun!

You know it’s steep when your hand is touching the snow, high risk high reward.

The snow report suggested 8 cm had fallen, it was more like 25-30 cm.

Now that he has a dirt bike the hunt is on for me too. This is the first ride trying to figure out the timing of the throttle, clutch and brake...second ride was even better.

Exploring Pinecone Burke Provincial Park a month ago with @troy.hartley. Standing in the site of the old ski lodge.

A well weathered tree coming through yet another winter with Yak Peak 2,039 metres in the background. Putting my limited artist talent to the test, these iPhones and filters making anybody a photographer.

A successful reconnaissance mission we crossed Falls Lake, ski toured up towards Zopkios Peak 1921 m. It was a exceptional picnic destination. The skiing was shit!

Who’s is going to go first?...I’ll go if you don’t! No friends on a powder day! @j_penner70 📷 @sheascottcolpitts

An epic day. Everything was perfect. Depth of Snow. Visibility. Temperature. Even the company.

In the green room today on the best coast amidst winter...not a bad place. 📷 @dgm_images

I saw this hat on Instagram, that very moment I knew I needed it. As a BC boy born and bred The Outdoorsman hat needed to be added to my collection. As someone who loves BC and most things outdoor, I’m now glad I have a cool hat to wear and fly the flag of BEAUTIFUL BRITISH COLUMBIA. It will be in my bag for all post-exploration celebratory cold pints. If you want to check them out or add one to your collection go to @nineoclockgun ...and yes my facial hair matches the hat as well.

When two of your ski buddies are 13 years old, you know you’re raising rippers. @paigerriley

My ski buddy getting untracked turns. It was knee to thigh deep all day for him, only shin to knee for me.

We went for a snowshoe this afternoon, but we probably should have considered taking our flippers instead. Our timing was off by one day.

From sea to snow capped peaks, it’s obvious why Vancouver and BC continue to be one of the best places to live. It’s engraved on our license plates, BEAUTIFUL BRITISH COLUMBIA.

Ancient blue glacier ice craving out deep valleys. It’s pretty cool standing underneath one...photo credit @dustanwoodhouse

This is a great start to the day!

No better way to share the great outdoors than with friends. @troy.hartley @mike_ilic711 @j_penner70

The ski out back to the truck was more of an adventure than we bargained for...

Exploring the BC backcountry, it did not disappoint...it never really does.

Thank god we are all narcissistic and have the ability to take pictures of ourselves 🤪. This is taken pre-turkey dinner, I’m sure we will all be back in our comfy clothes soon! Merry Christmas!

The crew shredding some turns , it was a 23,000 vertical foot kind of day.

Happy belated Hanukah, Merry Christmas and Happy Holidays to all. Be sure to enjoy the festivities.

Top of Swan Falls. I’ve said it many times before and I will say it again, our license plates say it all. BEAUTIFUL BRITISH COLUMBIA. #gooutside

The coveted annual mission to get our Xmas tree, with of course my Canadian tuxedo jacket on.

Yet another reason (unlimited really...) of why the Left Coast is the best coast! @tami0777

Moss, a non-vascular plant and Mother Nature’s carpet reclaiming the forest.

Capitalizing on a break in the wet coast rain storms.

Just follow the brown line switchbacking through Mother Nature. She’s so damn beautiful!

Day 3 for Black Magic was a bit snowier than initially expected. Thanks to the person who took a few minutes to build a snow creature.

Beauty day for a ride! I should have considered bringing my touring skis.

The West Coast is the Best Coast. #nofliter at sunset.

This was Day 1 on my @yt_industries Capra Pro 29. I thought the last bike was the best, it was a Capra Pro 27. I never thought the small differences in geometry and wheel size would have such a huge positive impact on my riding. Boy was I wrong! Best bike ever!

Oh boy! See a toy...buy a toy! New steed! YT Capra Pro 29 hitting the trails soon.

A tasty beverage while on the water yesterday from @backcountrybrewr and @backcountrybrewing

Epic ride with boys yesterday. Into the Mystic, Last Call, Happy Hour and Lord of the Squirrels. 5 hrs 15 mins, 31 km and 1,397 vertical metres.

Whistler slick rock is my favourite.

Wood to wood gap in Whistler.

Passing underneath the Ironworkers Memorial Bridge on the return journey of dinner-by-boat. No filter.

And now the training starts for Paris 2024 summer olympics.

Archery target: before, during and finished.

Aidan’s first day in the Whistler Bike Park, he had a blast and we rode trails I didn’t think we’d ride 😳. I’m sure we’ll return soon enough.

A rare sighting at the Whistler Bike Park, it’s been at least 10 years.

When the opportunity presented itself, I couldn’t pass up one of my favourite slick rock rolls.

Pre-dinner antics...it’s totally safe!

Aidan is captaining the watercraft, mom in just the passenger. Kalamaka Lake.

#Drewmboat camo @parksidebrewery

Safety first when roasting marshmallows.

Great place to press snooze for 20 minutes. Chez Labowka.


Raw kale. Just not the same as a kale caesar salad.

Saratoga Beach fire.

Canadian tuxedo.

Happy Canada 🇨🇦 Day to everyone near and far. I hope it’s a kick ass day. Play safe.

The @yellowdogbeer squirrel chaser or otherwise known as the chew toy was a hit with me and Moka Labowka

It’s always fun to start the trail with a repel. #mountainbike #climbing

It only took me a half dozen or so tries but I managed to cross the halfway line. This old guy still has it! Fun times.

Follow your path, at times you never know where it’s going to take you. Trust the outcome. Having fun in The Green Room.

This old guy was collecting a few air miles today.

Going vertical. #slickrock

I have a ski buddy, now it’s time to train a biking buddy.

I’m really looking forward to riding this gem once it re-opens. #burkeinmybackyard

Enjoying a distanced beverage with @senorwad @yellowdogbeer

Aidan and a couple buddies are now members at the Pitt Meadows Golf Club. @greggmcnally @genevemcnally @wendy22boddy @jaradboddy @kirstinjhallett

Raw and unedited. Old school skinny with a drop at the end.

I’m still HOME ALONE! Looking forward to the day when I’m able to have some friends over to share these @backcountrybrewing Widowmaker IPAs. #backcountryphotocontest

Zoa Peak, Coquihalla summit 1,500 vertical metres of skiing.

Distancing myself from the real world!

The dry land version of the @andrei_svechnikov37 lacrosse-style goal executed Aidan.

Skis or bike? Bike. The snow won’t stop me.

Does anybody need or want any firewood? It’s free...you come pick it up.

I needed to buck up the trees they fell in the last wind storm. Task complete.
View more
Why More Mortgage Options Matter—Especially for Assignment Purchases One of the biggest advantages of working with an independent mortgage professional is access to choice. Instead of being limited to one lender and one set of products, mortgage brokers work with multiple lenders—each with different guidelines, risk tolerances, and mortgage solutions. That flexibility becomes especially valuable when your situation doesn’t fit neatly into a “standard” box. A great example of this is purchasing new construction through an assignment contract . Why Assignment Purchases Can Be Challenging Assignment purchases are often viewed as higher risk by traditional lenders. Rather than declining these deals outright, many lenders quietly make them difficult by adding layers of conditions, restrictions, or uncertainty. This can lead to delays, frustration, or financing falling apart late in the process. The Good News There are lenders—available exclusively through the broker channel —that have clear, favourable policies for assignment purchases. With the right lender and proper planning, these transactions are absolutely doable. Typical Financing Requirements for Assignment Purchases While every situation is unique, many lenders that allow assignment financing look for the following: Standard purchase qualification, including income verification, credit, and down payment Assignments accepted at either the original purchase price or current market value Minimum 620 credit score , with no prior bankruptcies or consumer proposals The full down payment must come from the purchaser —seller incentives cannot be used Required Documentation To secure financing, lenders typically require: The original purchase agreement signed by all parties The MLS listing (if applicable) The assignment agreement signed by the builder, original purchaser, and new buyer Any side agreements outlining changes to the purchase price A full appraisal to confirm value This list isn’t exhaustive, but it highlights that while assignment purchases require more coordination, they are very achievable with the right lender and guidance. Final Thoughts Assignment contracts can open doors to great opportunities—but only if your financing supports the transaction. This is where access to multiple lenders and specialized policies makes a real difference. If you’re considering purchasing new construction through an assignment, or if you’d like to explore more traditional purchase options, feel free to connect anytime. I’d be happy to walk you through the mortgage products available and help you choose an option that doesn’t limit your financing possibilities.
You’ve found the right home, your offer’s been accepted, and your financing is approved—congratulations! But before you can pick up the keys and celebrate, there’s one more important stage: the closing process. Closing is the final step in your homebuying journey, where all the paperwork, legal details, and financial transactions come together. It can feel overwhelming if you don’t know what to expect, but with the right preparation, closing can be smooth and stress-free. Here’s a step-by-step guide to help you understand the process. Step 1: Hire a Lawyer or Notary A real estate lawyer (or notary, depending on your province) handles the legal side of closing. They will: Review the purchase agreement and mortgage documents Conduct a title search to confirm the seller has the legal right to sell the property Ensure the mortgage lender is properly registered on the title Handle the transfer of funds between you, the lender, and the seller Your lawyer or notary will be your main point of contact during closing, so choose one you trust and who communicates clearly. Step 2: Finalize Your Mortgage Your lender will send the mortgage instructions directly to your lawyer or notary. At this stage: You’ll provide proof of property insurance (lenders require this before releasing funds) You’ll confirm your down payment and closing costs are available in your lawyer’s trust account The lawyer will prepare all documents for your review and signature Step 3: Pay Closing Costs Closing costs typically range from 1.5% to 4% of the purchase price. These can include: Legal fees Title insurance Land transfer tax (where applicable) Adjustments for property taxes or utilities prepaid by the seller Home inspection or appraisal fees (if not already paid) Your lawyer will provide a final statement of adjustments so you know exactly how much is due on closing day. Step 4: Sign the Paperwork A few days before closing, you’ll meet with your lawyer or notary to sign all the necessary documents, including: Mortgage agreement Title transfer Insurance confirmations Statement of adjustments Bring valid government-issued ID to this appointment. Step 5: Transfer of Funds On the day of closing: Your lender sends the mortgage funds to your lawyer Your lawyer combines these funds with your down payment and pays the seller Legal ownership of the property is transferred into your name The lender is registered on title as a secured creditor Step 6: Get the Keys! Once the paperwork is filed and the funds have cleared, your lawyer will confirm that the transaction is complete. You’ll then get the keys to your new home—officially making it yours. The Bottom Line The closing process is a series of important steps, but with the right team in place, it doesn’t have to be stressful. By working closely with your mortgage professional and lawyer, you’ll have guidance every step of the way—from signing the documents to turning the key in the front door. If you’d like help preparing for the closing process—or want a clear breakdown of your own closing costs— connect with us today.